10 Ways Americans Endured the Great Depression, and Why Americans Today Are Completely Unprepared to Survive an Inferior Standard of Living
Seventeen thousand veterans camped on the Anacostia flats in the summer of 1932, most of them with wives and children, waiting on a bonus Congress had promised for 1945 and then offered early and then withdrew. Shacks went up out of packing crates and scrap. Cavalry and six tanks cleared the camps at the end of July, gas first, then fire, and the shacks burned through the night; two veterans died of it. The Bonus Army went home to nothing, and a country that had already watched nine thousand banks fail got a look at what its own government would do once the patience ran out.
Four years earlier the trouble had looked like a stock market problem, something confined to men in hats on Wall Street. Banks went first, then farms, then the factory towns, until twelve and a half million people stood idle and a quarter of the workforce had nothing to sell but its hands. Relief funds ran dry at city hall. Detroit’s welfare department began printing its own scrip. Chicago’s relief rolls went from seven hundred families in October 1930 to twenty-two thousand by the following April. Apple sellers appeared on Manhattan corners, six thousand of them by late 1930, and a fair number wore the suits they had been interviewed in the year before.
Underneath the catastrophe ran something the photographs catch only by accident, a working competence. Twenty million households kept a garden by 1934, municipal plots in Detroit among them, worked by men who had run lathes in 1929. Underwear got sewn from flour sacks that mills had learned to print in patterns. Fat went into soap. Shoes got relined with boot rubber and cardboard, since replacement cost more than repair. Extension agents printed bulletins on canning with a wash boiler. Farmers held penny auctions against their own banks, neighbors bidding a nickel on a neighbor’s harness and handing it back after the hammer, with the sheriff pretending to see nothing.
Most of that generation had grown up within one remove of a farm. Beans went up in jars on cellar shelves. Chickens got killed in back yards and butchered hogs hung in the cold. Poverty was the recent default, and the knowledge of how to live inside it arrived early, the way a language does.(A food crisis could kill millions of americans. are we on the verge of it? Watch this video to find out why.)
Half of that language is gone now. Three generations have known only the postwar escalator, and it ran long enough that they mistook it for a floor. A job for life if you stayed sober. A house that gained value while you slept in it. A pension or a matching contribution. Meat on the table, cooling in every room, orthodontia for the children, a week at the shore in August. Cheap oil, an unrivalled industrial base, a favorable demography and the reserve status of the dollar held all of it up, and every one of those supports has been thinning for twenty years while the expectations stayed nailed to the wall.
Credit filled the space between the paycheck and the expectation, and instant gratification did the rest of the work. Furniture on zero percent across forty-eight months. A pickup financed over eighty-four. Groceries split into four installments at the register. The dentist deferred to a card, Christmas deferred to a card, interest rolled forward quietly until the balance became a second rent. Early in the 1970s the country saved a dime out of every dollar. By April of this year it saved two and a half cents.
A population trained that way develops a temperament, and the euphemisms have worn thin enough to set aside. Americans have become whiny, self-absorbed and entitled, quick to grievance, slow to exertion, and markedly softer than their grandparents were at the same age. A late boarding announcement produces a queue of complaints. A day without power produces a neighborhood behaving as though a treaty had been broken. Small rehearsals, badly failed.
Household debt reached $19.1 trillion in the third quarter, five trillion more than at the end of 2019, with five percent delinquent, per the Federal Reserve Bank of New York. Credit cards crossed a record $1.29 trillion at a delinquency rate last seen fifteen years ago. Thirty-seven percent of respondents to a Federal Reserve survey published in May said a surprise $400 bill would send them borrowing, selling something or skipping it, and that survey went out at 4.1 percent unemployment, which happens to be the best the labor market can currently produce.
Food banks have become the country’s fastest-growing retail channel, and the growth tracks a policy change more than a harvest. Enrollment in the Supplemental Nutrition Assistance Program fell by more than 4.5 million people between the July 2025 enactment of the One Big Beautiful Bill and April 2026, according to the Center on Budget and Policy Priorities. Feeding America put the meal loss at up to nine billion a year, more than its entire network of pantries distributes. Freezers in Texas and Pennsylvania ran empty through the summer while the lines filled with people who held jobs and owned cars and had simply run out of month before they ran out of money.
Grocery prices rose 3.8 percent over the year. Twenty-two million seven hundred thousand renter households spend beyond thirty percent of gross income to stay indoors, twelve million of them past half. Medical obligations total roughly $220 billion, seventy-two million adults carry no dental coverage, and one adult in five skips the dentist over cost, a higher share than skips a prescription. Eleven point two percent of working-age adults have no insurance at all, up from 8.9 percent two years earlier. Residential electricity averaged 17.3 cents a kilowatt hour in 2025, with a projection of 18.2 for 2026 and a rise of twenty-seven percent since 2019. Roughly 698,000 people were counted homeless on a single night in January, which the government announced as a triumph because the figure had fallen six percent.
Two columns, laid beside each other, describe a movement in one direction. A generation that answered hard times with gardens, shared stoves, doubled-up households and neighborhood auctions has been replaced by one that answers them with a card, a subscription, an app and a complaint. What follows takes ten practices that carried people through the worst years of the twentieth century and sets each beside its modern substitute, which runs almost always to a purchase, a service, a screen or an assumption. Two of the ten are psychological. Those do the lasting damage, since a pantry refills inside a season and a temperament takes a generation to regrow.
Timing stays genuinely open. Debt at this scale can deflate across ten quiet years, each a little worse than the last, with the country adapting the way a frog warms. It can also break inside a quarter, the way Argentina’s convertibility broke across a weekend of frozen accounts and a peso that shed seventy percent in months. Household work comes out identical either way. Only the clock differs, and the clock decides how much time remains to remember what a great-grandmother knew without being taught.
1. They Planted on Vacant Lots, Canned With a Wash Boiler, and Sewed Underwear From Flour Sacks; We Keep Eleven Days of Food in a Garage and Call It Stocked
Hunger arrived as a supply problem in the 1930s and got answered as a production problem, a distinction the breadline photographs tend to bury. Municipalities handed out vacant lots and seed. Relief gardens in Detroit yielded millions of pounds of vegetables under the hands of men who had been machining parts three years earlier. County agents moved federal surplus commodities, school districts opened lunch programs in the hardest-hit places, and by 1939 the stamp plan let people buy surplus with orange and blue coupons. Much of the era’s food was repetitive and short on protein, and pellagra ran through the South on a diet of corn and fat, but the country could feed itself without waiting on a truck from a distribution center three hundred miles away.
Skills that made the home side of it work were ordinary at the time. Pressure canning, pickling, smoking, root cellaring, rendering fat for soap, cutting a garment down for a smaller child. Extension services published bulletins because the labor happened in kitchens and the kitchens needed instruction. Once mills noticed women sewing underwear from flour sacks, they began printing the sacks in patterns meant to be cut around.
Almost none of that survives in a modern suburb. Supermarkets keep two or three days of stock on the shelf and distribution centers a few days more. A 2023 survey conducted for a freezer manufacturer found the average household could feed itself for roughly eleven days on what it already owned. Eleven days handles a blizzard, handles a hurricane evacuation badly, and handles a disrupted spring hardly at all. Ice cream and frozen pizza fill the freezer in the garage. The root cellar became a finished basement. Goodwill took the pressure canner and set it beside a bread machine and a row of exercise bikes.
Money keeps eating the surplus that would have become a shelf. Groceries climbed 3.1 percent in 2025 and the Agriculture Department’s research arm projected another 2.7 percent for 2026, with beef above five percent before an autumn retreat. Feeding America’s Map the Meal Gap study found food-insecure households reporting they needed $23.16 more per person per week to reach basic nutrition. Short by twenty-three dollars a week, a household shops the perimeter, buys what gets eaten, and carries zero inventory into the next month.
Interruptions arrive faster than people expect. A diesel shortage or a closed bridge reroutes trucks into a delay, and seventy-two hours of delay empties shelves, driven as much by the sight of other people’s carts as by real scarcity. Panic buying converts a two-day problem into a two-week one, and panic is rational in a country where the average pantry is eleven days deep. Households with production capacity sit the panic out. Production capacity in a suburb means four raised beds, a compost bin and one spring of practice, which costs a few hundred dollars and a fair amount of attention.
Preservation counts for more than production, since July is a glut and January is a memory. Buy a tested pressure canner with a real gauge, the extension manual that goes with it, a hundred pounds of salt, a hand grinder, rice and beans in food-grade buckets with oxygen absorbers. Rotate the stock or it becomes a museum with better lighting. Learn to bake a loaf, kill and dress a chicken, render the fat for soap, roughly in that order of difficulty, and the household stops being a consumer of the food system and becomes a small participant in it.
Fuel and roads sit underneath all of it, and underneath those sits the producer. The farmer with an honor-system cooler at the end of the lane. The butcher who still breaks a half hog on order. The mill selling flour in twenty-five pound bags. The orchard selling drops by the bushel in September. Names matter in a way spreadsheets capture badly, and the households that eat through a shortage are the ones the producer recognizes at the counter. Building that recognition takes a year of ordinary Saturdays, which is the sort of thing that can be started this weekend and finished by next autumn.
Dirt under the fingernails carries a dividend nobody prices. Caseworkers promoting the relief gardens in the thirties understood them as morale measures as much as calorie measures and said so in their reports. Watching something grow through a bad month gives a household a reason to walk outside in the morning.
2. They Doubled Up, Held Penny Auctions, and Fought Eviction Crews in the Street; We Pay Half a Paycheck for the Right to Stay Indoors
Rent strikes rolled through the Bronx and the Lower East Side in 1931 and 1932, organized block by block. Crowds met the marshal’s men on the sidewalk and passed furniture back through the window as fast as it came out the door. New York alone recorded roughly 273,000 dispossess proceedings in 1932, with Chicago and Cleveland running their own versions. Countryside resistance took another form entirely, neighbors bidding a nickel on a neighbor’s harness at auction and handing it back after the hammer, stripping the bank of its recovery while the sheriff looked away. Iowa declared a foreclosure moratorium in 1933. Washington refinanced a million home loans through the Home Owners’ Loan Corporation, converting five-year interest-only balloons into long fixed notes and inventing the modern mortgage along the way.
Doubling up absorbed the rest. Lodgers moved in, families moved back to kin, and by 1933 a quarter of urban households were hosting somebody. The divorce rate fell, since two addresses cost twice as much as one bad marriage. Hoovervilles went up on vacant ground in Seattle, St. Louis and Central Park, and trailer camps outside industrial towns became a permanent feature of the migrant West. Building materials came off the scrap heap.
Renting has become the permanent condition for the young and the poor, and it has grown expensive enough to eat the cushion every month. Forty-nine percent of renter households were cost-burdened in 2024, past thirty percent of gross income, and 26 percent passed half, a record 22.7 million households and 2.3 million more than in 2019, per Harvard’s Joint Center for Housing Studies. Its 2026 report put cost burden above seventy percent for the poorest renters in every state and past ninety in some, leaving residual income too thin to reach much beyond the rent itself. Median asking rent in November sat near $1,729.
Three weeks of runway sits behind a family that has paid on time for six years. Filing in week three, court in week six, sheriff in week ten, moving truck costing more than the next deposit. The lease renews at whatever the market asks, and nothing gets built while the household waits.
Ownership turned into a lever somewhere along the line. Mortgage balances reached $13.4 trillion in the third quarter with the largest quarterly jump in years, part refinancing and part equity extraction, and a mortgaged house functions as an asset only while the payment clears. About a million nonfarm homes went to foreclosure during the Depression and roughly one farm in ten went under in the worst states, which explains the moratoriums and the penny auctions better than any theory of rural radicalism. Modern foreclosure moves faster and draws less collective sympathy, since the neighbors are strangers and the auction happens on a courthouse website.
Land is the half of the old arrangement that disappeared. A suburban quarter acre grows a serious quantity of food if somebody works it, and the typical owner keeps a lawn, a fence and a chemical service. Water and sewer bills arrive through a depression and hold priority over the mortgage in many jurisdictions, so a house dependent on a utility bill is a liability dressed up as an asset. Construction after 1980 assumes continuous heat, continuous power and permanently cheap energy. A house that freezes when the furnace quits fails in a gas interruption. Wood heat, storm windows, a basement that can be closed off, pipes that can be drained.
Mobility is the one advantage renting carries, and the boom years hide it. A tenant abandons a dying town inside a week. An owner with negative equity stays for years, and a crash erases the equity in the same quarter it erases the job, the trap that swallowed eleven million households between 2007 and 2016. Rural places trade walkability for self-sufficiency, a real trade with a real failure mode, since a rural household without a vehicle strands harder than an urban one and the distance to a cardiac unit turns lethal.
Defenses can be rebuilt in advance and most of them cost nothing. Put an occupancy agreement with a relative in writing while relations are still friendly. Learn the local eviction timeline and the name of the legal aid office before either becomes relevant. Get the roof, the furnace and the water heater into condition during a good year, because those three items are what a bad year converts into five figures. Clear title, small obligation, independent heat source, and somewhere to go that will take you in. The Depression generation treated those four as a package and pursued them with a discipline the modern household spends on choosing a streaming plan.
The US is Facing The BIGGEST Threat Of The Century!
So pay chose attention because this video will change your life forever for the good!
3. They Won Moratoriums on Their Mortgages; We Carry Nineteen Trillion Dollars and a Credit Card at Twenty-Two Percent
Credit before 1933 ran on short balloons that had to be refinanced at maturity, which meant a contraction forced simultaneous foreclosures regardless of whether the borrower had paid on time. Building and loan associations called in loans as their own depositors queued at the window, and the cascade took out solvent households alongside reckless ones. Farmers who had borrowed against a land price that collapsed could work a full season and still lose the place. What spread through the farm belt in 1932 and 1933 as a mortgage holiday movement was less radical economics than arithmetic wearing a political costume.
Relief came blunt. Moratoriums, HOLC refinancing, the Farm Credit Act, Frazier-Lemke relief in 1934, deposit insurance by June 1933, and a national revulsion against installment buying that held for a generation. People who lived through those years did their utmost to owe nothing, paid cash for cars when they could, and regarded a finance company roughly the way a modern household regards a payday lender. Zero-percent financing on a living room set, discovered by the grandchildren, must have looked like a gift from the store.
Modern obligation is enormous, layered and priced against the borrower. The $19.1 trillion the New York Fed reported for the third quarter splits into $13.4 trillion of mortgages, about $1.7 trillion of auto loans, above $1.6 trillion of student debt and a record $1.29 trillion on cards, with home equity lines growing at the fastest clip since 2005. Mortgages sit mostly fixed and mostly affordable for the cohort that refinanced cheap, which explains why housing credit has held. Revolving debt behaves the opposite way, repricing inside weeks and concentrating in households with the thinnest reserves. Twenty-two percent on a card held by a family saving 2.6 percent of income is a lit fuse. Auto loans carry a specific nastiness, since the car serves as collateral and as the means of reaching work, so three missed payments remove the income and the transport in the same week.
Buy-now-pay-later added a stratum the official statistics barely see. Volume runs into the tens of billions annually across four-installment plans, users stack several at once, and the product is engineered to feel like budgeting while behaving as a second, hidden card with weaker disclosure. Come a contraction, four schedules land in one week with no minimum payment to retreat to. Payday lending fills the space behind that at a triple-digit annualized cost, and the rollover is the whole business model.
Downturns work on a leveraged household through arithmetic. Income falls, the payment holds, savings cover the difference until savings end, and more debt at a worse rate covers it afterward. Then the minimum exceeds the income and the household starts eating its own maintenance, insurance first, then repairs, then food quality, then food. Every choice is rational in the month it happens and expensive by the second year. The $40 oil change deferred becomes a $4,000 transmission.
Triaging early beats triaging in a panic. Highest-rate balances go first, then the small fee-generating ones, then the subscription layer quietly billing through the card, which in an ordinary household runs past $150 a month for entertainment and cloud storage. Cutting that in a good month stings. Cutting it after a layoff is desperate and done badly. Credit unions price two to four points under national banks on identical product and use a less punitive model, and consolidation helps only if the cards then stay in a drawer.
Ordinary objects hide a good deal of debt. The financed sofa, the phone on a device plan, the mattress on eighteen months, the gym contract, the storage unit holding things nobody has opened in three years. Each is a small monthly claim, and the claims add up to a payment book that has to be fed before anything goes into savings. Storage units deserve their own line: a hundred and fifty a month to warehouse furniture is a mortgage on the past, and the honest calculation usually ends with selling the contents and keeping the cash.
Metal holds a narrow and genuine place here. Precious metal pays no coupon and makes no car payment, so it functions as a currency hedge and shows up only in the event where the unit of account itself breaks. Austrian hyperinflation, Argentina’s repeated collapses and the Soviet ending of 1991 ran the same pattern, in which people holding a little silver ate and people holding a bank balance ate less. Fractional coins beat bars, since a market has to make change. Whether the national habit swings back toward thrift through choice or through default stays open, and the default version is what the foreclosure columns look like from the inside.
4. They Sold Apples, Learned Trades on Relief Crews, and Marched on Ford’s Gate; We Bought a Degree on Credit and Lost the Habit of Repair
Anger came with the hunger and arrived first. The Ford Hunger March of March 1932 put several thousand unemployed men at the gates of the River Rouge plant and ended with four dead and dozens wounded by gunfire. Bonus Army veterans camped in Washington that summer, seventeen thousand of them with families, and got chased out with cavalry and gas. Midwest farmers organized the 1933 strike and dumped milk on the roads to make the price of hauling it visible. Huey Long proposed to cap fortunes, Francis Townsend proposed a pension at sixty, Upton Sinclair ran for governor of California on a plan to put idle factories back to work. Politicians responded to all of it because the alternative had become a crowd with a brick.
Work itself was a catastrophe officially and an improvisation privately. A quarter of the labor force stood idle, and the people who ate were the ones with a trade, a wagon, a needle or a still. Millions sold eggs, took in laundry, repaired shoes, peddled produce and rented rooms. WPA surveys found household income arriving from half a dozen sources at once with none of them sufficient. Apple sellers appeared on Manhattan corners by the thousands, most in shabby suits, and the sight became the era’s most durable image of status reversed overnight.
Federal programs absorbed a share deliberately. The CCC housed and fed three million young men in camps where they learned carpentry and mechanics beside the labor. The WPA eventually employed 8.5 million on schools, sewers and airports. The National Youth Administration put students on part-time jobs that kept them enrolled, and adult education ran through the same machinery teaching sewing, shorthand and small trades to people who had arrived without either. A collapsing economy still pays for repair, food, fuel and hauling, and it pays cash to whoever shows up with tools. That much has held in every collapse since.
October’s headline read well and concealed its own composition. Payrolls grew by 165,000 against a forecast of 59,000 and unemployment sat at 4.1 percent, with 7.07 million counted idle. Inside the same report, involuntary part-time work jumped 339,000 and hourly pay grew 3.1 percent against 3.7 percent inflation, which means the average worker took a real cut in the month the country celebrated. The alternative workforce is large and badly counted, 15.5 million on the narrow federal definition and near 73 million on industry surveys that include anyone earning a freelance dollar. Every arrangement in that range arrives without unemployment insurance, workers’ compensation or an employer contribution to anything. One worker in three now draws income from a platform, a 1099 or a schedule they control, and those workers absorbed the shocks of 2008 and 2020 by going without.
Specialization compounds the exposure. Four years and $80,000 buys a credential that is a fine thing while demand holds and a trap when it lapses, because it narrows what a person will consider and can afford to accept. The 1930s were full of trained people doing untrained work, architects selling apples, engineers on relief crews, lawyers driving cabs. A 1932 law graduate owed little. A 2026 one may owe $200,000 with a payment plan that survives job loss only through forbearance, and forbearance accrues.
Survivable work shares three properties and every one of them is boring. Low capital requirement, a customer who pays cash, demand independent of discretionary income. Roofing, plumbing, electrical, welding, small-engine repair, septic pumping, tree work, appliance repair, locksmithing, the medical trades, and the informal versions besides, hauling, sharpening, butchering, sewing, baking, childcare. Athens after 2010 ran on exactly that, and the neighborhood that ate had a butcher, a baker and a mechanic who took payment in kind. Buenos Aires in 2001 produced barter clubs with printed credits, and they held until the peso stabilized and the members drifted back to money.
Two obstacles have thickened since the last collapse. Licensing regimes now cover occupations that once needed a handshake, hair braiding and interior design among them, and the fees bite hardest at the moment entry matters. Platform companies inserted a dispatcher between worker and customer at twenty to thirty percent of the ticket, and a tradesman with his own phone number keeps all of it. Against that, community college night courses in welding and HVAC run a few hundred dollars, extension offices teach canning for the price of a jar, and volunteer fire departments train for free while begging for members.
Automation changes the shape of the next one. The 1930s were labor-hungry and could absorb people into public works, and the marginal worker was obviously worth a shovel. A downturn in the 2030s arrives with robots in the warehouse and a language model answering the phone, so the jobs that vanish first are the reading, sorting and answering jobs, the ones the middle class steered its children toward for thirty years. Whether the shovel still clears a wage is the question the next decade gets to answer.
5. They Printed Their Own Scrip When the Banks Locked; We Stand in a Banking Desert Holding a Phone
Nine thousand bank failures between 1930 and 1933 taught a generation to distrust institutions on sight, and the distrust produced habits that look eccentric until the context lands. Cash under mattresses. Savings in postal accounts. Gold coins sewn into coat linings. Tenino, Washington, printed wooden dollars on a planing mill in 1932, barter exchanges opened in dozens of towns and issued their own notes against goods delivered, and the March 1933 bank holiday froze every account in the country for a week. People learned precisely how much of their life sat in a ledger they could read only through a teller’s grille.
Deposit insurance ended the era of the ordinary run. Silicon Valley Bank showed in 2023 that a run can still happen at digital speed when $42 billion leaves in a single day. Mechanism changed, exposure did not. A balance is a promise, and a promise held by an institution under stress is worth what the institution’s liquidity says it is worth that afternoon.
Branch networks have contracted for fifteen years, past 1,200 closures in 2025 and 440 by July 2026, and 12.3 million people now live in what the Federal Reserve calls banking deserts, with another 11.1 million in potential ones. Rural definition is a branch more than ten miles off. Between 13 and 22 percent of branches in a recent merger batch were the last one within reach of their customers, which is why rural advocates have howled about the FDIC’s rapid approval track. What stands in the gap is an app, and the app performs beautifully until somebody needs to deposit cash, cash a neighbor’s check or argue a fraud hold with a human being.
Merchant habit squeezes cash more than policy does. Card-only kiosks, app-based meters, stadiums taking nothing else. Every card transaction throws off a fee and a data point, and both flow away from the household. A restaurant refusing cash also refuses the customer whose account is frozen, and the refusal happens at the counter with the food already cooked.
Mechanical failures outnumber systemic ones and arrive far more often. A fraud flag, a delayed payroll deposit, a card declined at the pump because a risk model disliked the zip code. In a normal month each is a day-long nuisance. In a month where rent is due and the balance sits at $61, the household discovers it owns no way to buy anything at all, and the discovery takes ninety seconds.
Split the reserve in two. Several hundred dollars in small bills in the house covers fuel, food and a motel room when the rails fail. A deeper reserve belongs somewhere that is a bank only by courtesy, a credit union, a safe, a relative’s attic. Currency risk supplies the other half of the argument. Argentina’s corralito froze withdrawals in 2001 and converted dollar accounts to pesos at a punitive rate. Cyprus imposed a haircut on uninsured deposits in 2013 and gave the template a name. Lebanese banks stopped paying out dollars after 2019 and turned the country’s savers into spectators of their own money. Each of those places had a modern banking system and a currency the world once respected, and none of them announced anything in advance.
Holding value outside the rails costs something, and pretending otherwise is how people get talked into nonsense. Cash loses to inflation, metal holds purchasing power at a spread, and neither produces income. A sensible split is a few weeks of cash, a modest position in fractional coins, and the rest in productive assets, tools, a vehicle that runs, land where affordable, the skills that convert one into another. Design against a month with the banks shut, the outer edge of plausible and far beyond the common case of three days.
An afternoon of paperwork belongs in the same category while the institutions still answer the phone. A second account at a separate institution, a paper statement kept at home, a copy of the insurance certificate, beneficiary forms checked and current, account numbers in a fireproof box. Half the misery of a bank failure is administrative, and administration is cheap in advance.
Programmable money will change the arithmetic of a reserve once it arrives. A central bank digital currency can be conditioned in ways a deposit cannot, and a condition can expire, restrict or gate a balance. Whether that lands as convenience or leash depends on decisions still unmade, and the safe assumption is that cash stays useful while fewer merchants want to touch it.
6. They Relined Shoes, Cut Their Own Firewood, and Made Soap From Saved Fat; We Call Somebody to Change a Tire
Competence in 1933 was the default setting rather than a virtue. Roughly half the population lived in a household keeping livestock or a serious garden. Roofs got patched, pumps got pulled, shoes got relined with boot rubber and cardboard, since replacement cost more than repair. Fat went into soap, flour sacks into clothing, worn sheets into rag rugs, and the whole household economy ran on a slogan every schoolchild heard: use it up, wear it out, make it do, do without. Unusual talent played almost no part in it. The knowledge circulated, and circulation was the whole mechanism.
Count what an ordinary household now subcontracts. Heat, plumbing, electrical, roofing, vehicle maintenance, food production, food preservation, medical triage, veterinary care, childcare, elder care, security. Every one has a professional attached, every professional earns the money while money exists, and in a contraction the professionals stay available while the money goes. The household does the work or lives with the consequence. Skipping a roof repair rots a deck, which is a skipped replacement, which is five figures.
Risk itself changes meaning once a person can do the work. Somebody who has replaced a water heater knows what a water heater does and how it fails, and that knowledge removes the panic from a flood. Somebody who has only ever held a phone treats the same flood as an act of God. The difference compounds in both directions, since a household fixing small things attempts larger ones and a household fixing nothing collects a list of small things that have all grown teeth.
Cheap routes into the knowledge sit everywhere. A service manual and a $40 mower off a classified site teach small-engine repair over a weekend. Tool libraries and maker spaces rent access to equipment nobody can justify buying. Extension offices teach pressure canning. Volunteer fire departments teach extrication while desperate for the help. Learn to sharpen a chain, sweat a joint and read a wiring diagram in whatever order suits you, and the order matters less than starting.
The trades are the serious answer and the market already prices them that way. Plumbers, electricians, welders, machinists and diesel mechanics all sit in shortage, all pay well, and all carry a license that travels. Industry projections warn of a shortage of several hundred thousand electricians this decade while grid rebuilding and data center construction pull at every certified body available. A twenty-two-year-old with a journeyman card and zero student debt stands in a stronger position than a peer holding a humanities degree and $120,000 of loans, a sentence that read as eccentric in 1995 and reads as arithmetic now.
Repair also reverses the household’s relationship to objects, which matters more than the money saved. A person who has fixed a dryer looks at the next appliance failure as a puzzle rather than a verdict, and the change in posture spreads to the car, the fence and the furnace. Children raised inside that posture absorb it without instruction, and the absorption is the transmission mechanism the last two generations lost.
Reading still helps, since manuals, regulations and the recorded history of other collapses all live in print. The failure mode is a household where everybody can analyze and nobody can solder. Find the side of that line your household occupies completely and cross it before the year turns.
One caution belongs here. Competence without practice rots the way any unused thing rots. A person who watched a video and owns the tool has a rumor of a skill, and the rumor collapses the first time the fitting is seized or the bolt snaps. Do the job once in a good month, badly, on a spare, and the second attempt belongs to somebody who has been there.
7. They Paid the Doctor With a Chicken and Took the Tooth Out Themselves; We Skip the Dentist and Hope It Holds
Plenty of the era’s doctoring happened at home and the rest happened cheap. Doctors took chickens and hams, county hospitals absorbed the indigent, extractions got done in kitchen chairs, wounds got cleaned with boiled water, and a good deal of the pharmacopoeia was whiskey, aspirin and a poultice. The 1935 Social Security Act built maternal and child health programs on top of a county clinic network that had been growing since the twenties. Doctors themselves went on relief in the early years, and the profession’s own journals carried columns about members taking farm work between patients.
One doctor, one bag, one bed. That was the supply chain, and shortness was its virtue. Effectiveness was the problem. Infection and malnutrition killed people whom modern medicine would have saved, and a bad appendix was a coin toss.
Both halves have inverted since. Capability soared and dependency soared with it, since survival now runs through cold-chain biologics, specialty pharmacies and a benefits administrator. Insurance stays bolted to employment, a wartime wage-control workaround from 1942 hardened into national architecture, which means a layoff strips coverage in the same envelope as the paycheck. COBRA arrives at a premium the newly unemployed can rarely pay. The uninsured rate among working-age adults climbed from 8.9 percent in 2024 to 11.2 percent in 2026, some 4.6 million more people, per the Commonwealth Fund’s biennial survey, which pinned the jump on expiring marketplace subsidies. Premiums rose nine percent across the same span, and 46 percent of working-age adults qualified as inadequately insured once the underinsured and the intermittently covered were counted.
Debt follows illness the way weather follows a front. Medical obligations total roughly $220 billion, more than a quarter of adults reported that they or a family member owed medical bills at the end of last year per the Urban Institute, and the median in collections among households carrying any came to $1,492. Around 15 million people have medical bills on a credit report, $49 billion worth, which converts a hospital stay into a rental application problem.
Dental disease works as the leading indicator because it is the most skipped category of care in the country. One adult in five forgoes it over cost, a higher share than skips a doctor’s visit or a prescription, and 72 million adults hold no dental coverage at all, with the uninsured rate among adults under thirty at 34 percent. An abscess can kill. The emergency room drains one, bills the patient and sends them home with the tooth still in place. Nearly all of it is out-of-pocket, which makes dentistry the first thing a strained budget drops and the last thing it restores.
Prescriptions track the same path, with about a third of underinsured adults delaying or skipping medication over cost. Insulin, inhalers and thyroid tablets share the profile of cheap manufacture and captive pricing, and a diabetic skipping two days of insulin reaches an emergency department with a bill ten times the copay avoided. Chronic disease supplies the structural difference from the 1930s, since six adults in ten carry at least one chronic condition and four in ten carry two, and a population on metformin and a biologic cannot live on short rations the way the population of 1933 could.
Preparation here is dull and effective. Refill early where a plan allows and rotate the stock. Ask for a paper script as a backup. Learn which medications have cheap cash equivalents and what they cost on a discount card. Finish the dental work while income exists, because a crown now beats an extraction and an implant later. Keep a first-aid kit genuinely stocked and learn to use it. Walking helps, and a garden helps twice, producing food and exercise with measurable wellbeing effects in trial after trial.
Some practical knowledge deserves reviving because it fills the gap between the household and the clinic. How to take a temperature, how to recognize dehydration, how to clean and dress a wound, how to splint a finger, how to tell a sprain from a break, how to manage a fever in a child, and which of the bottles in the cabinet actually do something. Wound care alone prevents more misery than any other single skill, and the supplies cost less than a dinner out.
Time is the thing money cannot buy back. A tooth aching for a year gets pulled during a crisis, which is a poor season to be healing from anything.
8. They Knew Every Name on the Block, Bartered Through Cooperatives, and Filled the Church Kitchen; We Know the Delivery Driver’s First Name
Self-help cooperatives appeared in California, Utah and Washington between 1931 and 1933, organized by the unemployed to produce and barter among themselves, and at the peak there were close to a hundred in California alone. The EPIC movement in that state proposed production for use rather than profit and won enough votes to terrify the establishment. Soup kitchens and clothing rooms ran out of church basements in nearly every city. The Salvation Army and the Community Chest funneled private charity. Fraternal lodges kept death benefits paid through years when dues came in slowly. A man who belonged to something had a network, and the network was the difference between a bad year and a lost decade.
Fifty years of thinning have followed. Robert Putnam documented the collapse of associational life through the 1990s and the trend kept going after his book sold. Church membership fell below half the population for the first time in 2020 and continues down. Union density sits near ten percent. Bowling leagues dissolved and took the alleys with them.
Thinner and mostly commercial is what replaced the ties. Groceries, food, a date, a ride, a therapist and a dog walker all arrive from a phone without a word to anyone within a mile. Convenience is real and the cost is deferred, since the network that once caught a household now exists as a roster of vendors who stop appearing when the card declines.
Mobility finished the job. The average American moves nine or ten times in a life and the long moves follow work, so the neighbors at the current address have known each other a few years and nobody carries a history with anybody. Two generations beside each other, as in the 1930s, built an obligation that a three-year acquaintance cannot. The penny auction worked because the bidders had grown up alongside the man losing the farm, and a courthouse website attracts strangers.
Kinship carried the era’s heaviest freight. Doubling up was the standard answer to eviction, a quarter of urban households hosting lodgers or relatives by 1933, and that arrangement is hard to reach with a family scattered across four states and speaking twice a year. Rebuilding takes years, which is why it belongs in a good one. Learn the six nearest names. Volunteer for something weekly, since frequency builds obligation faster than enthusiasm. Join the fire company, the pantry, the church kitchen, the library board.
Reciprocity needs a ledger and the ledger needs a first entry. Give first, give cheaply, give a jump start, a ride, a loaf, an hour with a chainsaw. A neighbor who has received something remembers it. A neighbor who has received nothing has no reason to answer the door, and the test arrives as a car that turns over badly on a cold morning.
Congregations deserve their own paragraph because they are the most resilient institution in the inventory and the most neglected. Buildings, kitchens, lists of the needy, a doctrinal reason to help, volunteer labor sending no invoice. Churches ran the soup kitchens of the 1930s and the federal relief apparatus copied their methods afterward. Inside a congregation a household owns a distribution network and a set of people who notice when the lights stay off.
Union halls and trade associations carry the same function in another register. A hall is where a laid-off member hears about work before it gets posted, and where dues from good years return as a strike fund or a death benefit. Family supplies the last piece, small and far apart now, fertility at record lows and the median distance to a parent growing. Evacuating to a hotel rather than a spare room is what awaits a household with no sibling inside a day’s drive, and that negotiation runs far easier before anybody is desperate.
An inventory of the local network costs an evening and repays itself within a year. Who has a truck. Who has a generator. Who has medical training. Who keeps a spare key. Who is home during the day. Who has a well, a woodlot, a boat, a trailer, a chest freezer, a pickup with a plow. Most neighborhoods hold far more capacity than anyone realizes, and the capacity stays invisible until somebody asks a question out loud at a block meeting or over a fence.
9. They Rode Boxcars, Walked Ten Miles for Work, and Heated With Coal and Wood; Our Geography Requires a Full Tank of Gas
Hoboes rode the rods by the tens of thousands and a man could cross from Kansas to Oregon without a ticket, sleeping in jungles beside the yards and eating at back doors. Trolley lines still threaded most cities, torn out at precisely the moment they would have proved most useful, and the photographs of the era are full of soles worn through. Five and ten miles of walking went into a day’s search for work, since sitting still paid nothing.
Coal came down a chute and wood came off the woodlot. Refrigeration came up the back stairs on a wagon, and fewer than one household in ten had an electric refrigerator in 1930, the icebox being a piece of furniture with a drain pan. Kerosene lamps stayed in the cupboard against the night the power failed, and the power failed often. A broken car put the owner under it, because a mechanic’s bill was a week’s wages.
Around the car, and then around the second car, the modern country organized itself. Roughly 92 percent of households own at least one vehicle and the average household owns about two, and land use has followed that assumption since the war. Options under a fuel shortage go to the household with two cars in a walkable town. The household with one car in an exurb gets nothing, and the exurb holds a great deal of the country.
Electricity prices climb underneath all of it. Residential rates averaged 17.3 cents per kilowatt hour in 2025 with the Energy Information Administration projecting 18.2 cents for 2026, summer peaks running higher and several states posting double-digit increases as utilities file for data center and transmission capital. National residential rates rose about 27 percent since 2019. A Harvard and Penn study attributed roughly four percent of the five-year increase to data centers, smaller than the political argument implies and enough to keep climbing. The grid itself is old where it counts, graded C-minus by the civil engineers, most transmission past its design life, and a queue of new generation waiting years for interconnection. Weather keeps proving the point. The February 2021 Texas event darkened 4.5 million households and killed more than two hundred people, most of them from cold inside their own homes.
Measure the radius first, which costs nothing. Anything inside a twenty-minute walk belongs to survivable territory and everything past it depends on a machine, so ranking the grocery, pharmacy, school, clinic and hardware store by how many fall within that circle tells you more about a home than its square footage.
Fuel storage runs easier than people expect for gasoline and harder for diesel. Stabilized gasoline in approved cans holds six to twelve months and rotates with a monthly habit. Propane stores indefinitely and runs a camp stove, a heater and a grill. A woodstove with two cords of dry hardwood heats through a winter and requires a sweep and a wood source, both arranged ahead of the season. Vehicle resilience comes down to keeping one machine genuinely sound and knowing the cheap failures, a spare that holds air, a jump pack, belts, filters, a manual. Changing a tire in the dark and rain takes twenty minutes to learn and saves a night.
Walkability carries a premium and the premium buys an option. A small town with a grocery on Main Street, a clinic and a school inside a half mile is a different risk profile from a subdivision eight miles out, and the difference never shows up in a mortgage rate. Rural places trade the walk for self-sufficiency, a different bet with a different failure mode, since a rural household without a vehicle strands worse than an urban one.
Heat and cooling get the last word because they kill fastest. A house without heat in a northern January is a three-day problem and a house without cooling in a Phoenix August is a two-day one. A generator solves neither unless sized, fueled and vented, and most portable units manage none of the three for a whole house. One room sealed with blankets and warmed by a propane catalytic unit keeps a family alive. The rest of the house keeps the pipes.
Bicycles deserve more respect than they get. A bicycle with a rack and panniers moves a week of groceries five miles and costs less than a single car payment, and the fitness that comes with it doubles as medical insurance. A trailer turns the same bicycle into a light hauler. Towns built before 1945 have the streets for it and towns built after have the shoulders.
10. They Were Bored, Fatalistic, and Hard; We Are Entertained, Optimistic, and Soft
Depression living is tedious long before it turns dangerous. Same cheap meals, same cold rooms, same worn clothes, same walks to the same places, same evenings with nothing to spend. The diary entries of the 1930s are stupefying in their sameness, and a population raised on streaming video and next-day delivery has almost no practice at sameness. Hunger is a problem; boredom is a mood, and the mood grinds people down in ways the problem does not.
Entitlement supplies the other half, trained rather than chosen. Retirement at sixty-two, a car under five, air conditioning in every room, meat several times a week, a vacation, orthodontia, a college fund per child. Historically recent, every one, and guaranteed by nothing. What shocks people about losing them is discovering they were never promised, and the discovery arrives as an insult rather than as information.
Fatalism was the era’s dominant mood, sometimes paralyzing and sometimes useful. Useful versions assumed things would be bad and had to be managed, and they produced the penny auction, the garden, the shared stove, the borrowed truck. Inversion is what the modern mood amounts to. Somebody will intervene. When somebody fails to, the yelling starts, and the yelling is a way of waiting.
Preparedness literature handles mindset badly, all wolves and warriors, when the concrete version is smaller. Eating the same meal four days running without comment. Being cold for an hour. Walking while a car sits in the drive. Repairing rather than replacing. Waiting. Being the calm one in the room. Rehearsal covers all of it, by turning the heat off for an evening, cooking from the shelf for a week, taking the bus while the car stays parked.
Children need the rehearsal most and get it least. A child who has gone hungry, cold and bored owns a frame for the first bad month, and the frame matters more than the calories. Depression children carried the habits into the 1960s, raised the most comfortable cohort in history, and that cohort raised the least prepared one. Transmission broke across two generations and broke fastest in the richest households, where the margin for discomfort was widest.
Ritual helped, and the ritual was functional rather than decorative. Church attendance rose, radio audiences for the fireside chats ran to tens of millions, and the Federal Theatre Project drew twelve million people to free performances. Dance marathons filled halls, Monopoly arrived in 1935 and sold out, and a nickel bought a double feature. Crowds gathered to be told things were bad and would continue, and the gathering carried as much weight as the words. Alcohol belongs in the same category, legal again from December 1933 partly for the tax revenue, consumed more heavily as the decade wore on. A case of cheap spirits stores indefinitely and trades well.
Blame rounds it out. Hoover, bankers and the previous generation’s speculation took the weight in the 1930s, all of it largely correct and largely useless. Blaming whoever holds office lands in the same place now. Dropping the litigation and working the problem is how households get through, and working the problem doubles as a treatment for despair.
Anxiety management deserves a specific word because the modern default runs toward a screen, and screens make waiting worse. A book, a deck of cards, a radio, a guitar, a whittling knife, a hand-cranked flashlight occupy an evening without electricity and without a bill. Sitting with a neighbor in silence is a skill worth learning. The 1930s porch was a technology for this, and the porch has been replaced by a deck nobody sits on.
Consolation sits inside the record itself. The people who lived those years were ordinary and thought of themselves that way, and most found they could do considerably more than they had believed. Capacity stays in the population. Dormant differs from absent, and practice wakes dormant things before necessity does, which is the whole argument for starting in a year like this one.
What the Ten Comparisons Add Up To, and the Twelve Months of Ordinary Work That Would Change the Answer
Read the ten sections as a single ledger and the pattern stops being about individual habits. Substitution runs the same way in every one of them, from a household that produced, repaired, stored and knew its neighbors toward a household that buys, subscribes, finances and waits to be rescued. Inefficient, uncomfortable and unglamorous, the old arrangement still worked through four consecutive years in which the official unemployment rate ran between fourteen and twenty-five percent, a third of the banking system failed, and the country’s own weather turned on it in the Dust Bowl. A mild recession and a three-week supply shock are the only tests the new arrangement has faced.
Worth admitting, since the comparison flatters the past: the 1930s household was more capable and lived worse. Pneumonia killed people who would survive today. A broken femur could end a working life. Infant mortality ran at levels that would be a scandal now, and a woman with an ectopic pregnancy had a coin toss. Modern medicine is a genuine inheritance and the argument here stands on top of it rather than against it. What the country did was trade resilience for capability in some domains and comfort in others, and it made the trade without ever pricing it.
Deposit insurance exists, sitting beside $19.1 trillion of household debt and a 2.6 percent saving rate. Unemployment compensation exists, sitting beside the thirty-seven percent who cannot raise $400. Social Security exists, and its retirement trust fund runs dry in the fourth quarter of 2032 on the trustees’ own 2026 projection, at which point 78 percent of scheduled benefits stay payable. Medicare’s hospital fund follows later on the same arithmetic. Real protections, all three, and all three assume a functioning Treasury, a functioning Congress and a functioning currency, assumptions that have held for ninety years and are being tested in public.
Heroism was never the historical answer, whatever the popular memory insists. Improvisation, neighborliness and a federal government that eventually built institutions carried it. Control over the first two sits in the household; the third sits beyond reach. What the 1930s had that the 2020s lack is a culture in which improvisation was normal. A garden in 1933 was a garden among gardens, and the man who dug one could ask three neighbors how to do it. A garden now is an eccentricity, and the eccentric learns alone.
Reversing that starts small and starts now, and the list has the virtue of costing almost nothing. Rice in a bucket, salt, oil, a hand grinder. Cash in a drawer in small bills. A pressure canner and the manual, used twice before it matters. A dentist appointment made while there is income and insurance. A coat that fits each member of the household, bought in April. Half a trade learned, badly, in a night course. Six neighbor names memorized and one favor given before it is needed. A written agreement with the relatives about who takes whom. A bicycle with a rack. A woodstove, or at minimum a catalytic heater and a sealed room. A paper copy of every account number in a fireproof box. Drama stays low, waste stays at zero, and the same preparations carry a bad year and improve a good one.
Timing deserves a straight answer, so here it is. Debt at this scale can deflate across ten quiet years, each slightly worse than the last, with wages losing a point a year to prices and the country adapting the way a frog warms. It can also break inside a quarter, the way Argentina’s convertibility broke across a weekend of frozen accounts and a peso that shed seventy percent in months. Greece took five years and lost a quarter of its economy in increments. The Soviet Union ended with a currency that stopped being money and a state that stopped answering the phone, and the people who came through had a garden, a trade and a dacha. How much time a household has to remember what a great-grandmother knew without being taught is the only variable that separates the slow version from the fast one, and households that start early get the slow version whether or not the slow version arrives.
Two things make this decade harder than the last comparable one. Reading, sorting and answering jobs vanish first now while a robot takes the warehouse shift, so the traditional absorbers have narrowed. Debt carried into the contraction is the second, since a household with $30,000 on cards enters a layoff already behind, and the 1930s household entered with a mortgage and little else. Depression borrowers had the advantage of owing against assets that could be renegotiated, and renegotiation happened because a million people made noise in the street until Congress wrote a law.
Some national advantages are real and belong on the page. The United States grows more food than it eats, holds the world’s reserve currency, sits on the largest energy reserves of any developed nation, and retains a deep bench of technical skill inside a shrinking but still formidable industrial base. A country holding those cards can absorb a great deal. A population that has forgotten how to do anything for itself it cannot absorb cheaply, because the forgetting converts every disruption into a purchase, and purchases require money, and money requires the system to keep humming.
Nobody in the 1932 photographs knew they were living through a historic event. They were trying to reach the spring. Their great-grandchildren are trying to reach a paycheck, and the distance between those two ambitions is the distance this article has been about. One of them is a horizon. The other is a habit, and habits can be changed on a Tuesday afternoon in November while the power still works and the shelf still holds eleven days of food.
Anyone can join.
Anyone can contribute.
Anyone can become informed about their world.
"United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
Before It’s News® is a community of individuals who report on what’s going on around them, from all around the world. Anyone can join. Anyone can contribute. Anyone can become informed about their world. "United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
LION'S MANE PRODUCT
Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules
Mushrooms are having a moment. One fabulous fungus in particular, lion’s mane, may help improve memory, depression and anxiety symptoms. They are also an excellent source of nutrients that show promise as a therapy for dementia, and other neurodegenerative diseases. If you’re living with anxiety or depression, you may be curious about all the therapy options out there — including the natural ones.Our Lion’s Mane WHOLE MIND Nootropic Blend has been formulated to utilize the potency of Lion’s mane but also include the benefits of four other Highly Beneficial Mushrooms. Synergistically, they work together to Build your health through improving cognitive function and immunity regardless of your age. Our Nootropic not only improves your Cognitive Function and Activates your Immune System, but it benefits growth of Essential Gut Flora, further enhancing your Vitality.
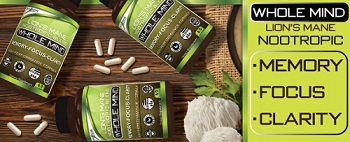
Our Formula includes: Lion’s Mane Mushrooms which Increase Brain Power through nerve growth, lessen anxiety, reduce depression, and improve concentration. Its an excellent adaptogen, promotes sleep and improves immunity. Shiitake Mushrooms which Fight cancer cells and infectious disease, boost the immune system, promotes brain function, and serves as a source of B vitamins. Maitake Mushrooms which regulate blood sugar levels of diabetics, reduce hypertension and boosts the immune system. Reishi Mushrooms which Fight inflammation, liver disease, fatigue, tumor growth and cancer. They Improve skin disorders and soothes digestive problems, stomach ulcers and leaky gut syndrome. Chaga Mushrooms which have anti-aging effects, boost immune function, improve stamina and athletic performance, even act as a natural aphrodisiac, fighting diabetes and improving liver function. Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules Today. Be 100% Satisfied or Receive a Full Money Back Guarantee. Order Yours Today by Following This Link.

| Visits: | 1,838,893,111 |
| Stories: | 8,739,030 |
Whistler Blowers, Insiders

