The Stock Market’s Looming “Ground Stop”
This past Friday the 13th, I flew into Pittsburgh and landed just before a “ground stop” closed U.S. airspace and snarled travel over the weekend. As I exited the airport, status screens were lit up with delay notices. Weather? No. It was every flight, everywhere. Something was wrong.
The public explanation is chronic government neglect of aviation infrastructure, and that may be true; parts of our nation’s air traffic control system still run on 1960s, ’70s and ’80s hardware. But the episode shows something larger: how a complex system can become brittle when the custodians treat it like old furniture.
Meanwhile, our financial system is much the same. It’s brittle and ready to break. Indeed, unfettered, Wild West-style dealmaking has inflated new asset bubbles: in AI, in AI-related “pick and shovel” plays, and in real estate; and a long list of companies appear primed to take serious hits.
In general, stock markets don’t care what you want; they care about what’s hot, or at least what sells. And over many years I’ve followed energy and mining plays, and people who raise Big Buck$ to dig things out of the ground. So, in this sense, I’ve “seen the movie,” so to speak: the original, the remake, the remake of the remake. Same plot, different costumes.
Today the storyboard is premised on silicon. The sound stage is huge data centers financed by eye-popping levels of credit, along with suppliers to a massive buildout, and by extension an inflated real estate market. Call it a casino with a credit line.
Chip makers – think Nvidia – lend to their own customers; while other private lenders fund even more projects that nobody can properly value; and speculators borrow against their own inflated shares to fund more “investment,” if not lifestyle. And this extends to real estate and housing, of course, goosed via easy credit. But as history teaches, bubbles rest on borrowed money and borrowed time.
The point is that the AI boom is no longer just a technology story; it’s more of a high-risk lending story. Nvidia alone arranges and backs hundreds of billions of dollars in financing for the data centers that buy its chips, with big banks and private equity firms lining up beside it.
All in all, we have a multi-trillion-dollar (yes, “trillion” with a “T”) shadow economy of private credit; that is, loans made outside traditional rules, to finance projects that are hard to value, all because the business plan is mostly arm-waving and speculation.
Many investors, meanwhile, borrow against their tech shares to buy houses, cars and more tech shares. Do you see the circle? The lender, the borrower and the collateral are often the same entities wearing different hats.
But big cracks have appeared in the proverbial dam. For example, last summer the $45 billion Situational Awareness fund went into forced liquidation in under three weeks. And right now, another large fund called Lone Pine Capital is on the ropes.
More broadly, a recent headline in Bloomberg News stated that Major Hedge Funds Mostly Lose in ‘Nowhere to Hide’ October, with much of the blame pinned on the decline of AI and related tech shares. So, clearly, we have a warning of distress for investors here.
Then there’s Nvidia, whose share price has collapsed by over a third in the past five weeks, from about $240 in early October to under $160 just now, erasing roughly $2 trillion in market cap. Oh, and its CEO resigned, while the U.S. government is concerned about the company’s back-channel relations with Communist China.
All this, and Nvidia is reportedly talking to insurers about covering its loans against default, which may ring a bell: remember AIG and the insurance it wrote on mortgage bonds? Insurance didn’t remove the risk; it stacked another layer of risk on top.
Loans to Assets That Cannot Repay
The problem is that a loan is only as good as the cash flow from whatever it finances. A data center that costs billions must earn billions, year after year, to service its debt and replace chips that go obsolete in a few years.
Much of today’s AI spending rests on projections of revenue that don’t exist and may never reach the scale promised. Construction jobs vanish when the building is finished, while the tax breaks that lured the project drain local budgets.
When a borrower can’t repay, what does a lender seize? Perhaps a shell full of aging servers in a big building that’s hard to repurpose. That’s not collateral for investors who want their money back; no, it’s more like grist for the slow-moving mills of bankruptcy lawyers.
Something similar happened in the 1980s. Westinghouse had a subsidiary called Westinghouse Credit, which lent funds to buyers who bought the company’s products, such as steam turbines. The idea was that a finance-loan against productive machinery would be repaid over the service life; a very sensible business, until easy money beckoned.
Then, Westinghouse Credit took on second- and third-position loans in consumer and property markets (eg., roadside motels, restaurants, housing developments), which placed it subordinate to long lines of other lenders. When the banking and housing bubbles popped, those junior positions were wiped out, and a great industrial name was brought to its knees.
The lesson? When an industrial company starts acting like a bank, look out.
The Recession Is Already Here
Wall Street talks about a “recession” as if it were a hurricane still far out at sea. In the real economy, it looks more like the storm has made landfall for millions of Americans.
At household levels, foreclosures are rising. Auto repos are climbing. Credit card balances are going bad. And many student loan borrowers are in limbo as collections resume.
None of these is a big headline alone, but together they outline a consumer sector that has outrun its cash. Meanwhile, a handful of giant AI names prop up the stock market, which masks the damage; so, the indexes say “boom” while Main Street says “bust.”
This is America’s two-track economy: those who own stocks can spend, while everyone else cuts back. The arrangement holds only until the stock market stops going up.
Fast or Slow?
Will the looming decline be fast or slow? Nobody knows but…
A fast decline begins with a catalyst: a failed financing, a data center loan default, or a bond market tantrum as foreign holders trim Treasuries and yields jump. The result is a brutal, short selloff. Then comes relief as people buy the dips. Retail investors decide the bottom is in, and everyone rushes back into a bull trap, which is how fortunes are lost.
A slow decline would be a steady grind lower, bank by bank and quarter by quarter, as losses surface and credit tightens.
On my end, I expect a sharp shock down, then a convincing but fake rally, all leading to a bad-loan crisis by about March or April of 2027. The mess will work through the system next year and into 2028. It’s a scenario, not a prophecy.
We’ve Seen This Movie
In 1837, trouble followed the demise of the Second Bank of the United States. President Andrew Jackson vetoed its recharter, leaving banking without an anchor. It’s a long story, but basically, America was in a depression into the 1840s.
In 1873 it was railroads. Companies laid track far ahead of traffic, financed by bonds sold to eager investors in the U.S. and overseas. Jay Cooke and Company, the nation’s premier banker, failed that September. Then the stock exchange shut for ten days, and the Long Depression that followed lasted many years.
By the 1890s, overbuilding had spread from rails to heavy industry. The Panic of 1893 took down hundreds of banks and thousands of businesses amid a drain on the nation’s gold reserves. At one point the U.S. Treasury ran out of money and the federal government was flat broke.
In 1929 the high flyer was RCA, the Nvidia of its day, a radio company whose shares soared on a technology that would change the world. But in 1929 – 30, RCA fell to a fraction of its peak, as did the broader market, where margin debt had been the fuel. The Dow lost close to 90% by 1932.
Housing has its own history. In the 1980s, Texas oil-patch banks and many savings and loans collapsed under bad energy and real estate lending, and roughly a third of the thrift industry failed. And between 2002 and 2009, subprime mortgages were bundled into bonds, many insured by AIG, which cratered as Lehman Brothers fell.
Every one of these episodes follows the same pattern: a new go-go story, easy credit, collateral that can’t service the debt, and finally forced liquidation. Today’s story is AI, but the old pattern is unchanged.
Safety, and the “No-Bid” Problem
So, where can investors find some semblance of safety?
Hold cash. It’s not glamorous, but it gives you options, and during a crash buying power is worth more than any forecast.
Plus gold, because central banks continue to buy it and it’s nobody else’s liability. I expect gold to move up strongly in 2027 as the crisis deepens and the Federal Reserve cuts rates to goose the economy.
Still, be careful with gold because, in a “no-bid” market, many things find no buyers at any price, and investors must sell what they can, not what they want. When margin calls arrive, people can’t raise much by selling stocks that crashed; so, they sell the assets that still hold value, and that means gold.
In late 2008, for example, gold fell sharply as funds liquidated positions to raise cash. So, yes… even precious metals can decline in the first leg of a crash, and you shouldn’t count on gold being up in week one. But gold tends to recover fast.
Three Things You Can Do Now
- Raise cash. If you can, build a reserve of six to twelve months of expenses, plus dry powder in short-term Treasury bills. Trim speculative AI and crypto positions into any rally, especially the bull trap I described.
- Own gold, patiently. Buy physical metal in measured size, pay with cash rather than borrowed money, and expect volatility. Be a holder, not a trader.
- Cut debt and counterparty risk. Pay down credit cards and variable-rate debt, avoid margin and loans against your stock portfolio, and keep deposits within insured limits across more than one institution. Know who owes you money, and whether they can pay.
Lastly, make sure you’re getting a respectable APY on your savings. If you’re looking for an innovative bank in the rocky environment to come, get familiar with Battle Bank. It’s a new bank founded by Rick Rule and Frank Trotter, two of the top guys in the business. Battle Bank currently pays 3.45% on checking and saving accounts, allows you to buy and store precious metals, and offers a host of unique services.
Please note that Paradigm Press is a marketing affiliate of Battle Bank and may receive compensation when you open an account. Precious metals are not FDIC insured, are not bank guaranteed, and are subject to market risk, including possible loss of principal.
Learn more about Battle Bank here.
And that’s all for now. Thank you for subscribing and reading.
This story originally appeared in the Daily Reckoning
Source: https://dailyreckoning.com/post/the-stock-markets-looming-ground-stop
Anyone can join.
Anyone can contribute.
Anyone can become informed about their world.
"United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
Before It’s News® is a community of individuals who report on what’s going on around them, from all around the world. Anyone can join. Anyone can contribute. Anyone can become informed about their world. "United We Stand" Click Here To Create Your Personal Citizen Journalist Account Today, Be Sure To Invite Your Friends.
LION'S MANE PRODUCT
Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules
Mushrooms are having a moment. One fabulous fungus in particular, lion’s mane, may help improve memory, depression and anxiety symptoms. They are also an excellent source of nutrients that show promise as a therapy for dementia, and other neurodegenerative diseases. If you’re living with anxiety or depression, you may be curious about all the therapy options out there — including the natural ones.Our Lion’s Mane WHOLE MIND Nootropic Blend has been formulated to utilize the potency of Lion’s mane but also include the benefits of four other Highly Beneficial Mushrooms. Synergistically, they work together to Build your health through improving cognitive function and immunity regardless of your age. Our Nootropic not only improves your Cognitive Function and Activates your Immune System, but it benefits growth of Essential Gut Flora, further enhancing your Vitality.
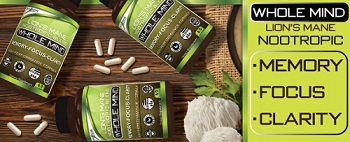
Our Formula includes: Lion’s Mane Mushrooms which Increase Brain Power through nerve growth, lessen anxiety, reduce depression, and improve concentration. Its an excellent adaptogen, promotes sleep and improves immunity. Shiitake Mushrooms which Fight cancer cells and infectious disease, boost the immune system, promotes brain function, and serves as a source of B vitamins. Maitake Mushrooms which regulate blood sugar levels of diabetics, reduce hypertension and boosts the immune system. Reishi Mushrooms which Fight inflammation, liver disease, fatigue, tumor growth and cancer. They Improve skin disorders and soothes digestive problems, stomach ulcers and leaky gut syndrome. Chaga Mushrooms which have anti-aging effects, boost immune function, improve stamina and athletic performance, even act as a natural aphrodisiac, fighting diabetes and improving liver function. Try Our Lion’s Mane WHOLE MIND Nootropic Blend 60 Capsules Today. Be 100% Satisfied or Receive a Full Money Back Guarantee. Order Yours Today by Following This Link.

| Visits: | 1,838,893,111 |
| Stories: | 8,739,030 |
Whistler Blowers, Insiders

